
Transition to Retirement
What is a TTR strategy?

What is a TTR and how does it work?
A Transition to Retirement (TTR) strategy sounds complex, but we’ll show you in detail who it’s for, how it works, and provide real examples of how it can be used in different situations. We’ll also explain how to set one up.
What's covered in this guide:
How a 'Transition to Retirement' strategy works
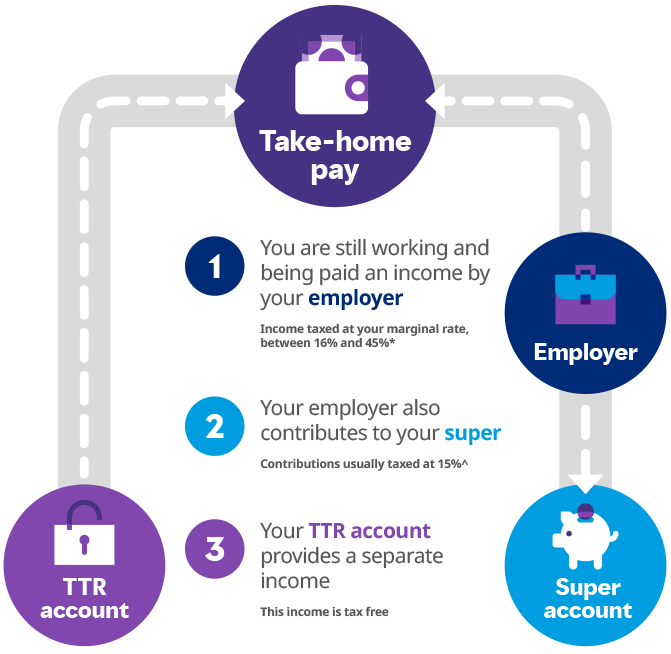
- For members between the ages of 60-64, a TTR strategy is used while you're still working and receiving an income from your employer.
- You will receive employer contributions to your super, usually taxed at 15%, which may be lower than the tax you pay on your take‑home pay.
- Meanwhile, your TTR account can pay you a regular tax-free payment to top up your take-home pay.
You can choose to receive TTR pension payments yearly, half-yearly, quarterly, monthly or twice monthly. You can draw a tax-free income of between 4% and 10% of your TTR account balance each financial year.

How can a TTR strategy help me ease into retirement?
Depending on your personal circumstances and financial goals, there are three ways you can use a TTR strategy between ages 60 and 65. Let’s look at these options through the example of Naveen, who has just turned 60.
Meet Naveen
- Naveen has just turned 60 and is still working. Monthly income before tax: $8,191.
- Monthly take-home pay (after tax): $6,359.
- Super balance: $300,000.
- Naveen opens a new TTR account and transfers $270,000 into it.
The following examples are intended as general information only and should not be considered personal advice. Calculations and figures are approximate only and are based on 2026-27 income tax rates. We recommend you seek financial advice tailored to your personal circumstances.
Need help?
As a Mercer Super member, you can speak to one of our dedicated super specialists to explore your future income options, at no extra cost.

3 ways to use a TTR strategy effectively
1. Semi-retire without losing income
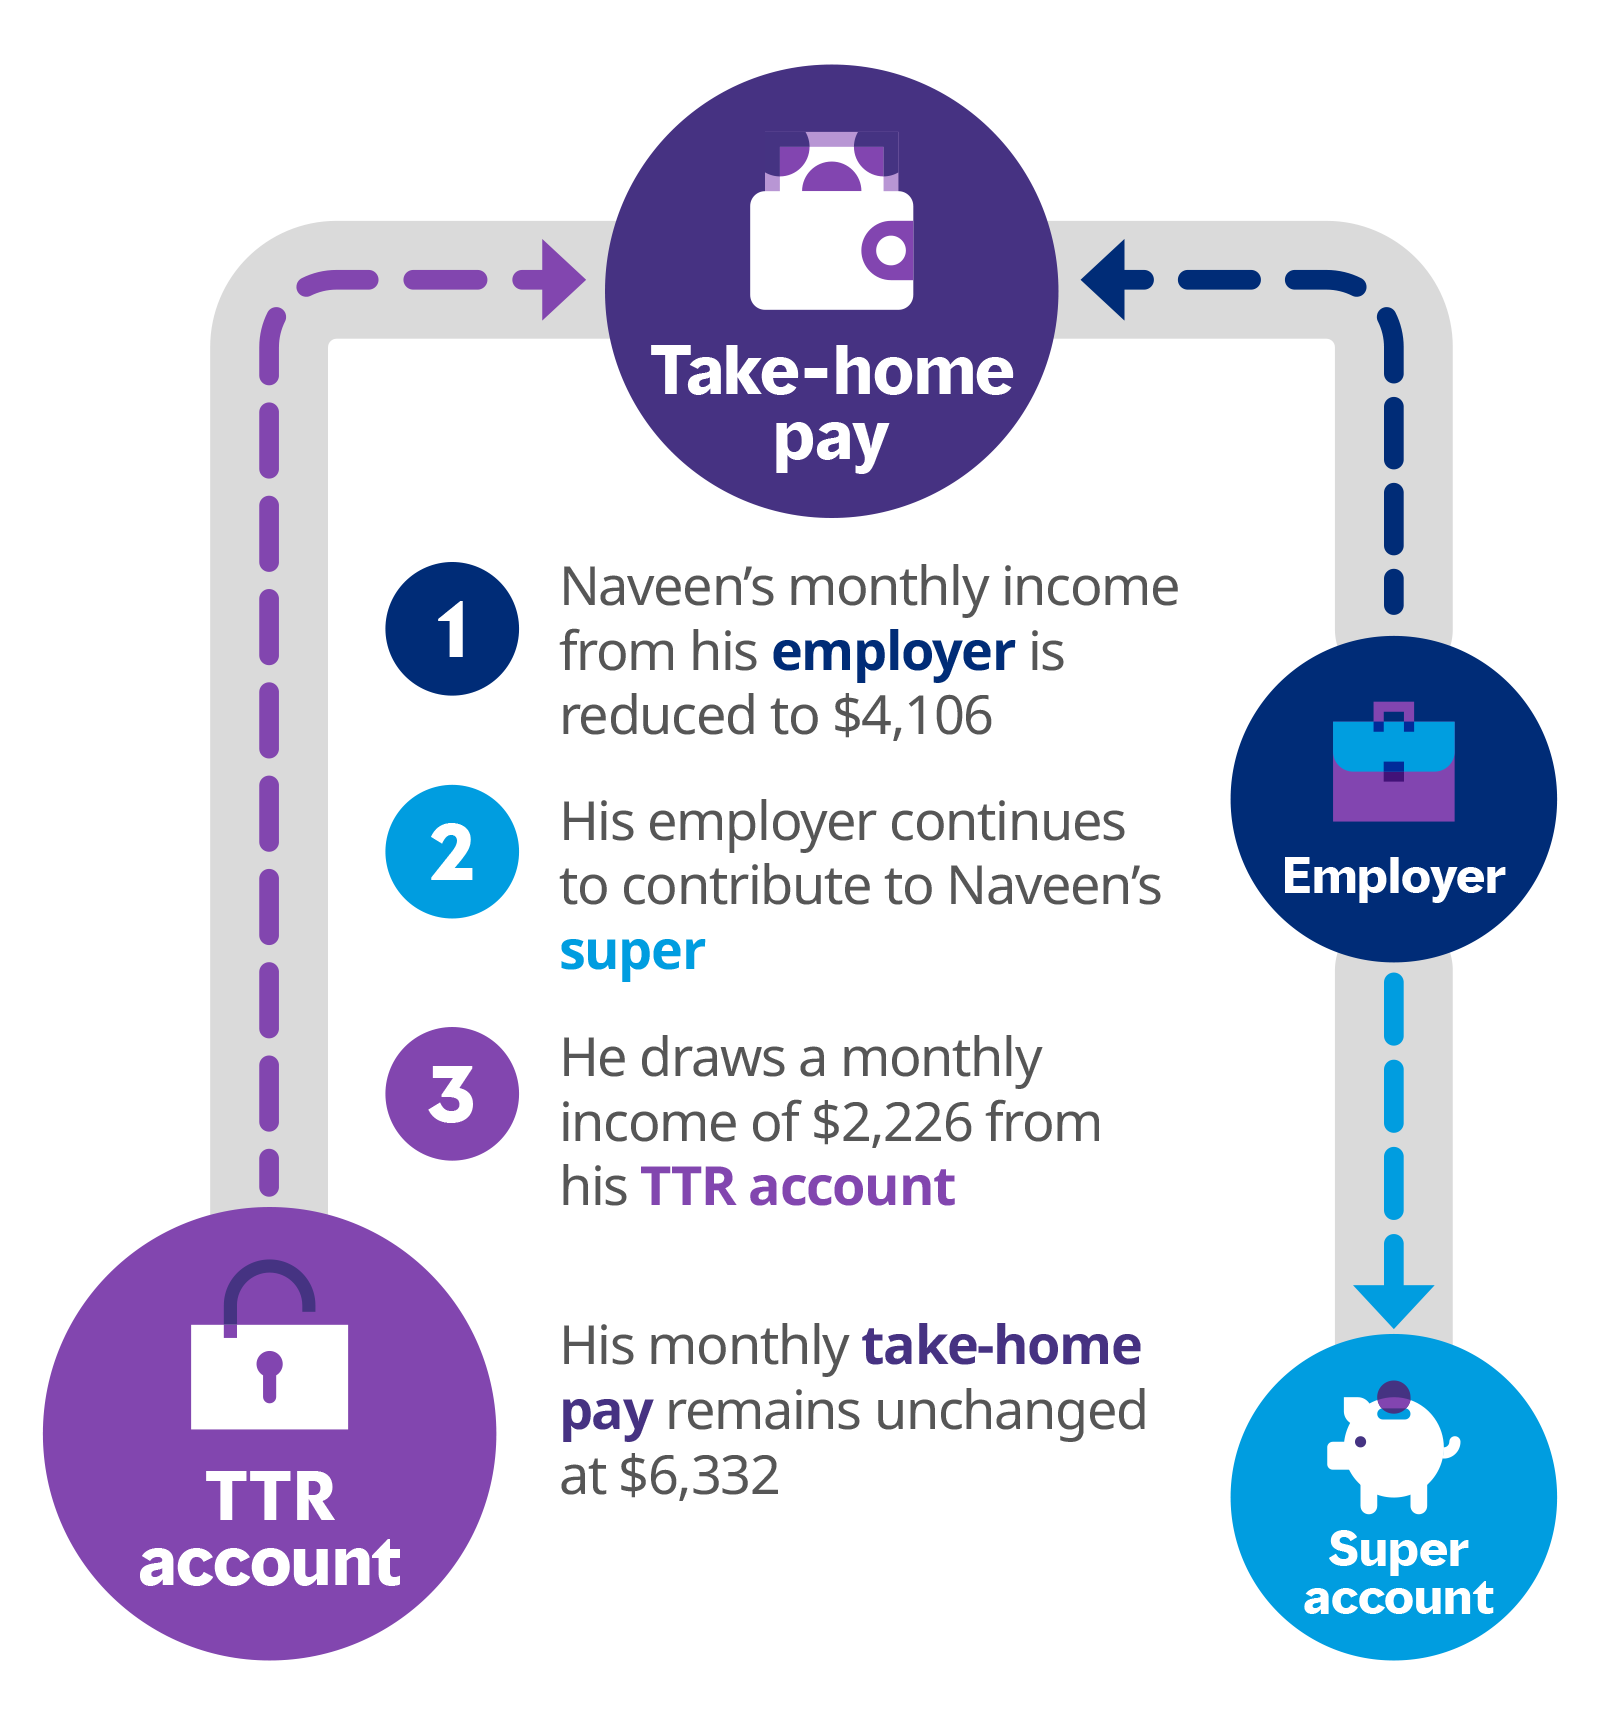
Naveen wants to cut back his work hours while maintaining his current take‑home pay. He reduces his working week from five days to three, lowering his pre‑tax salary by 40%.
Naveen’s monthly take-home pay reduces to $4,142.
- His employer continues to make super contributions to Naveen’s super account.
- Naveen makes up the difference in take-home pay by drawing a monthly income of $2,217 from his TTR account.
His total take-home pay remains unchanged at $6,359.
2. Boost your super savings without losing income
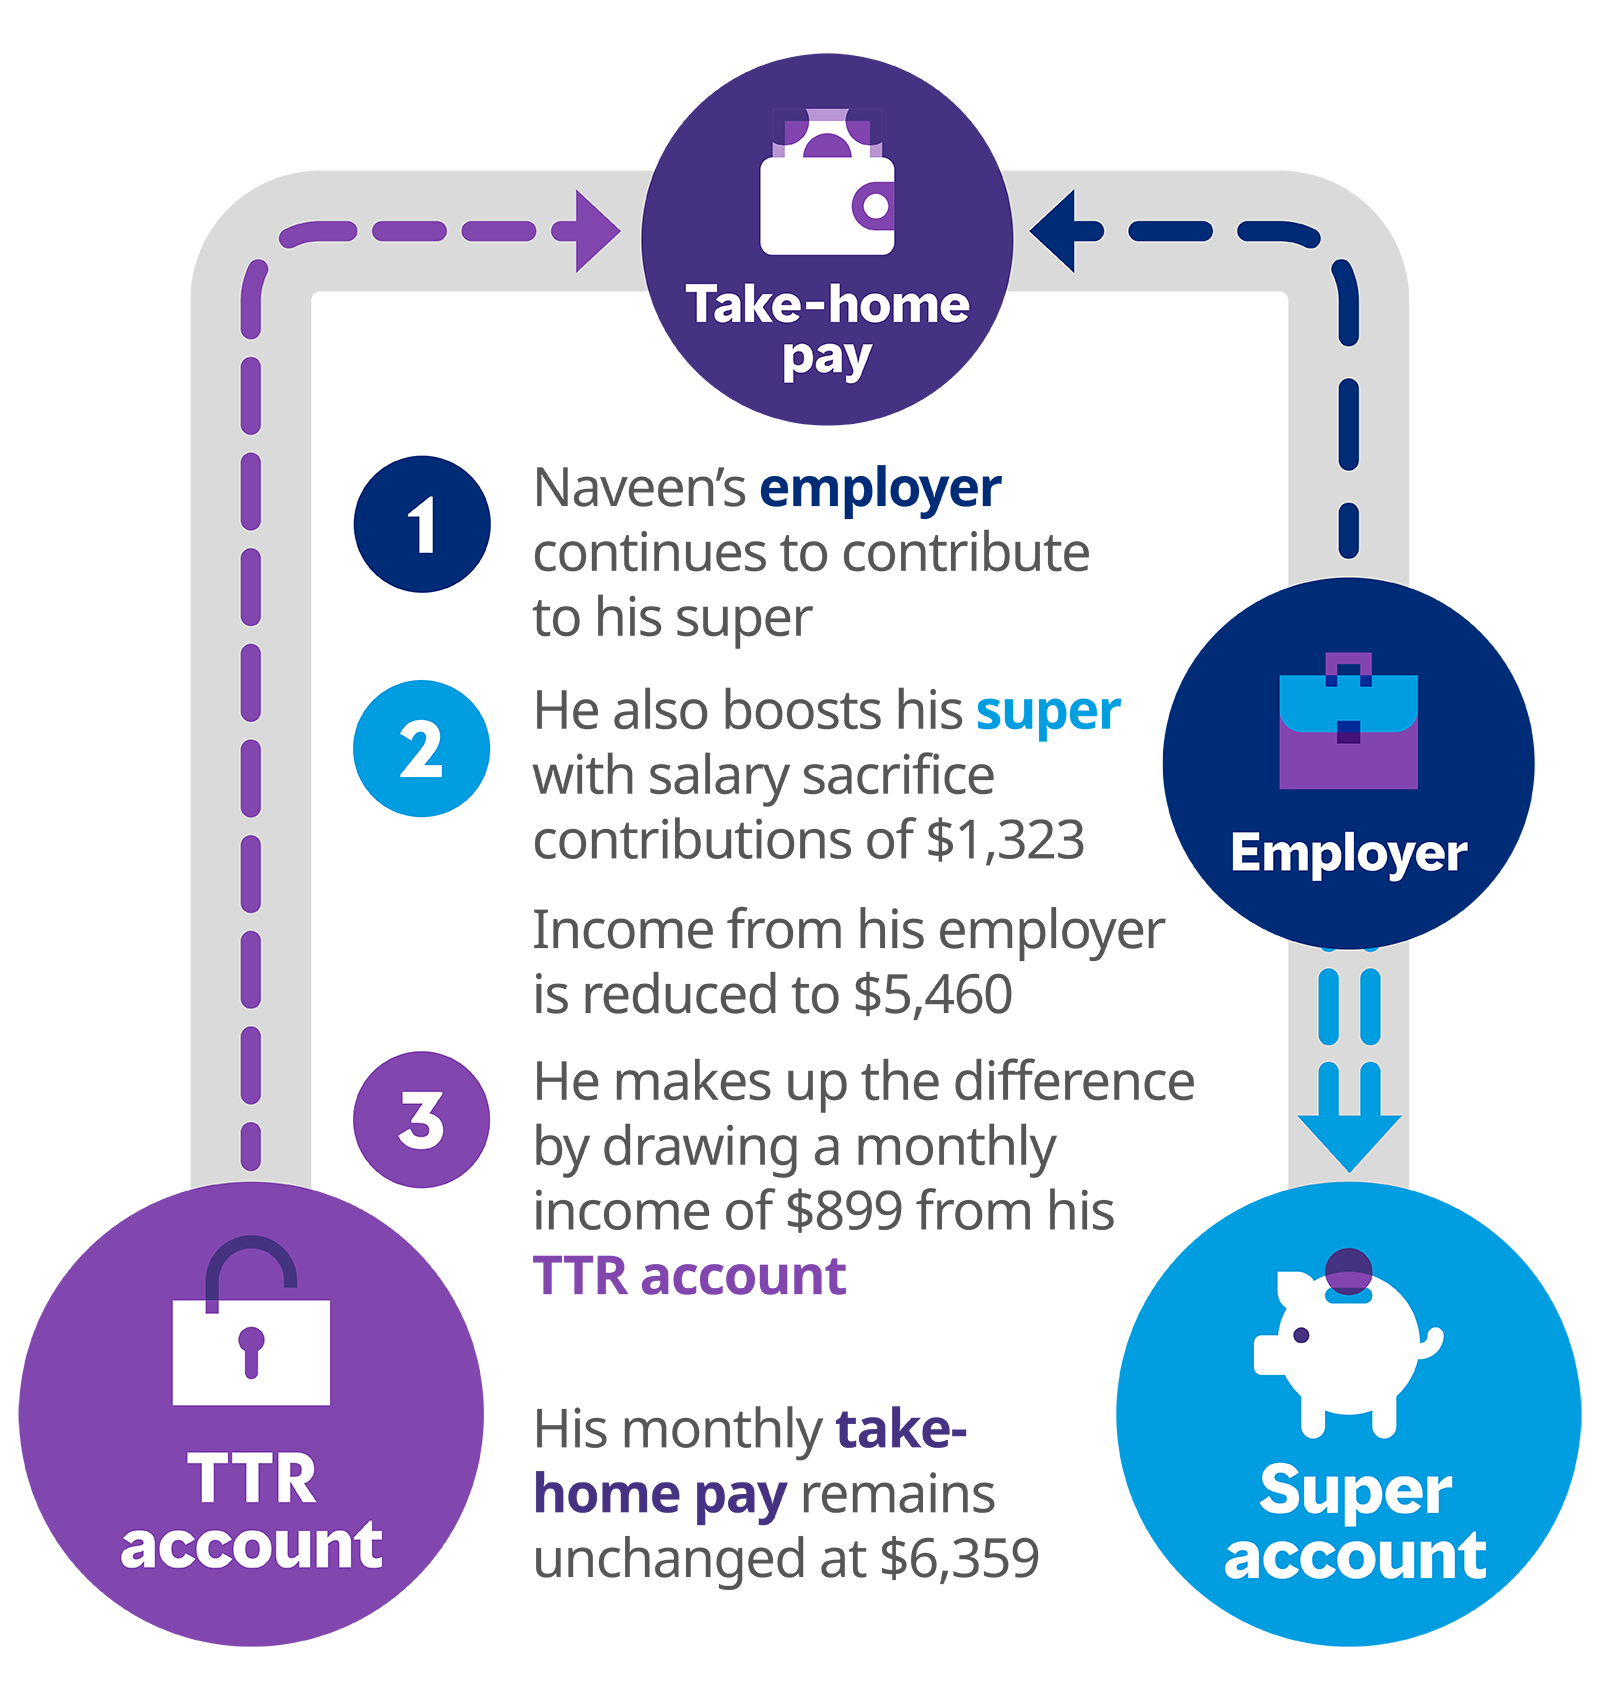
This strategy allows Naveen to boost his super with salary sacrifice contributions without reducing his take-home pay. Naveen continues to work five days per week (full-time).
- In addition to his employer contributions, Naveen salary sacrifices $1,323 each month into his super account.
- His before-tax salary reduces to $6,868 resulting in his monthly take-home pay being reduced to $5,460.
- He makes up the difference by drawing a monthly income of $899 per month from his TTR account.
His total take-home pay remains unchanged at $6,359.
Did you know?
By salary sacrificing to super, Naveen may be able to save over $5,000 income tax over the financial year, money that would otherwise have gone to the Australian Tax Office.
3. Access some of your super to pay for large expenses
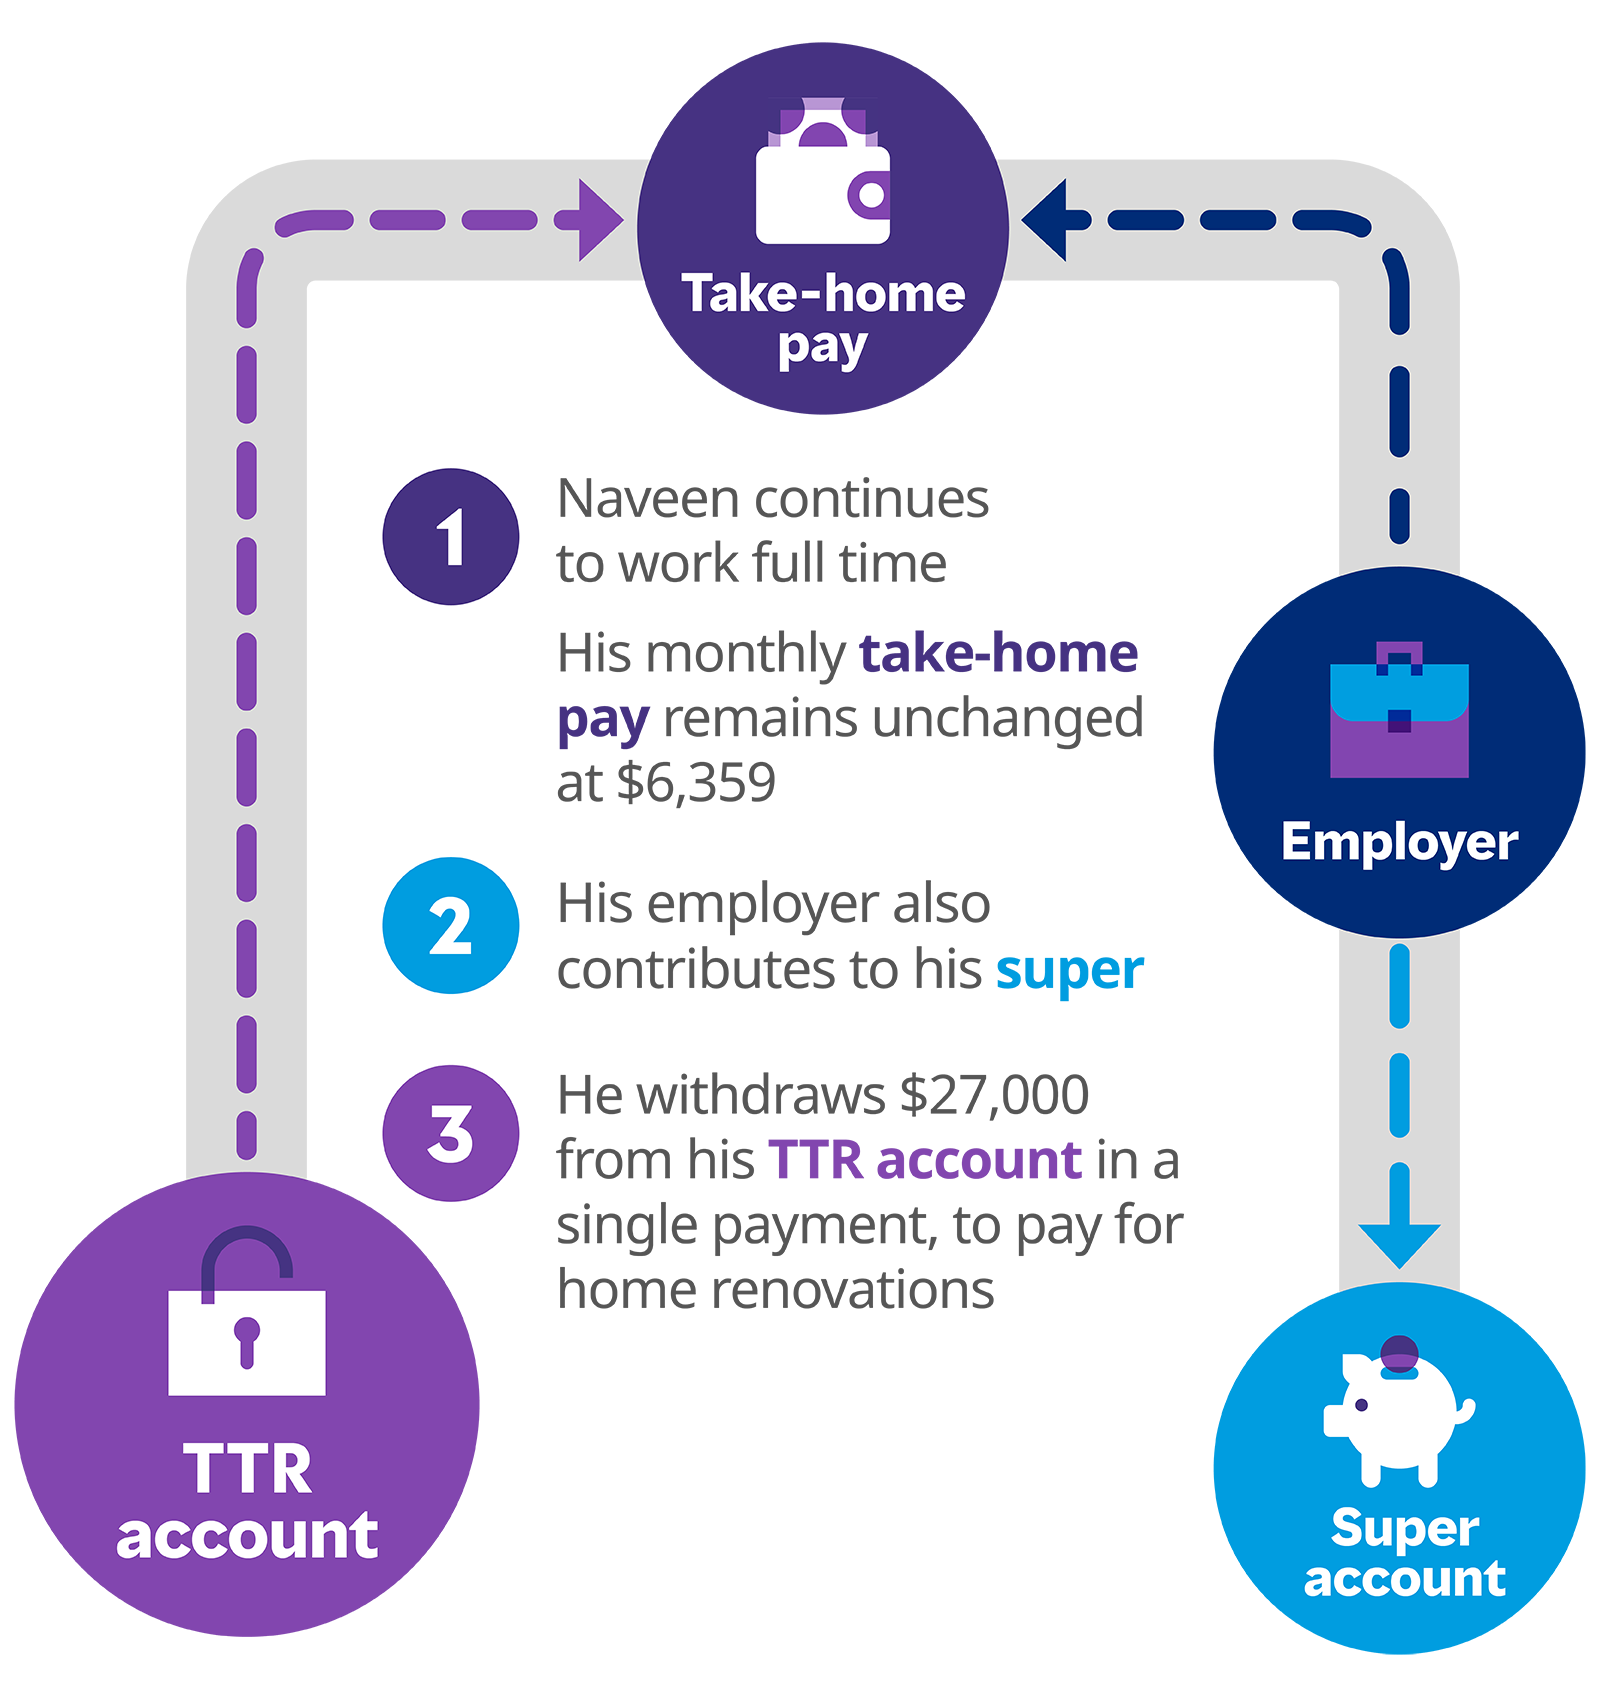
In this example, Naveen uses his TTR account to access part of his super to help meet large expenses. He can withdraw up to 10% of his TTR account balance each financial year to pay for big ticket items like paying off his mortgage or renovating his home.
- Naveen continues to work full-time, and his regular monthly income remains unchanged at $6,359.
- His employer continues to contribute to Naveen’s super account.
- To pay for home renovations, Naveen withdraws $27,000 from his TTR account in a single, annual payment (within the 10% limit).
These examples show some of the ways a 'Transition to Retirement' strategy can be used. A TTR strategy may not be right for everyone and they can also be complex, particularly in its implications for contributions caps and tax laws. We recommend seeking financial advice to understand what’s right for your personal circumstances.
Advice and tools, whether you need a little help or a lot
No matter where you’re at in life, the right advice at the right time can help you take charge of your super and retire with confidence. With Mercer Super, tools and guidance are always within easy reach.

Setting up a TTR account
What you need:
- You must be over 60 and under 65
- You need two accounts:
- Your regular super (savings) account
- A TTR pension account.
What to do:
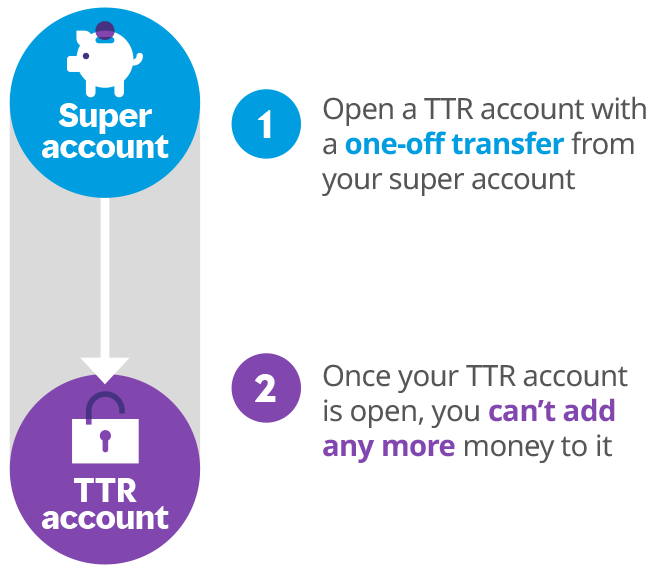
- Open a TTR account
- Transfer part of your existing super balance into that TTR account.
Important to know:
- You can’t add money to a TTR pension account.
- Employer Super Guarantee (SG) contributions and any extra contributions go into your regular super accumulation account.
- Both accounts, your super account and the TTR pension account, stay invested and can often use the same investment options.
- Investment earnings in both accounts are generally taxed at 15%.1
Quick Tip
If you have insurance through your super and want to keep it, you may need to leave your super account open with enough to cover premiums. This could also be an opportunity to review your insurance cover to make sure it meets your needs.
Explore more: it’s your time to thrive
Will my super go the distance?
Not having enough money saved for a comfortable retirement and outliving retirement savings is one of the biggest financial worries for people worldwide.

How do I turn my super into income?
More Australians are continuing to work past the traditional retirement age to help their retirement savings last longer. Explore your options of working through your retirement.

Working in retirement
Retirement doesn't always mean you stop working completely. In fact, many Australians are working longer than ever before, some because they want to, others because they need to.
1 Investment returns can be subject to tax if the total of all of your super and pension accounts exceeds $3m.
Issued by Mercer Superannuation (Australia) Limited (MSAL) ABN 79 004 717 533, Australian Financial Services Licence 235906, the trustee of Mercer MyChoice which is part of the Mercer Super Trust ABN 19 905 422 981 (‘Mercer Super’).
Any advice provided is of a general nature and does not take into account your objectives, financial situation or needs. Before acting on any advice we recommend you obtain your own financial advice and consider the Product Disclosure Statement and Financial Services Guide available by logging into your account.
‘MERCER’ is an Australian registered trademark of Mercer (Australia) Pty Ltd ABN 32 005 315 917.
Past performance is not a reliable indicator of future performance. The value of an investment in the Mercer Super Trust may rise and fall from time to time. The investment performance, earnings or return of capital invested are not guaranteed.
The trustee has appointed Mercer Financial Advice (Australia) Pty Ltd (MFAAPL) ABN 76 153 168 293, Australian Financial Services Licence 411766 to provide financial advice services for members of the Mercer Super Trust. Mercer Financial Advisers are authorised representatives of MFAAPL.
Any information on tax in this document is based on our interpretation of current tax laws which are subject to change. We recommend you obtain your own tax advice when considering the application and impact of tax laws that may affect you. No warranty as to the accuracy or completeness of this information is given and no responsibility is accepted by Mercer or any of its related entities for any loss or damage arising from reliance on the information.